Maldives Pushes Forward with 1,273 Projects as Economy Signals Recovery Amid Global Pressures
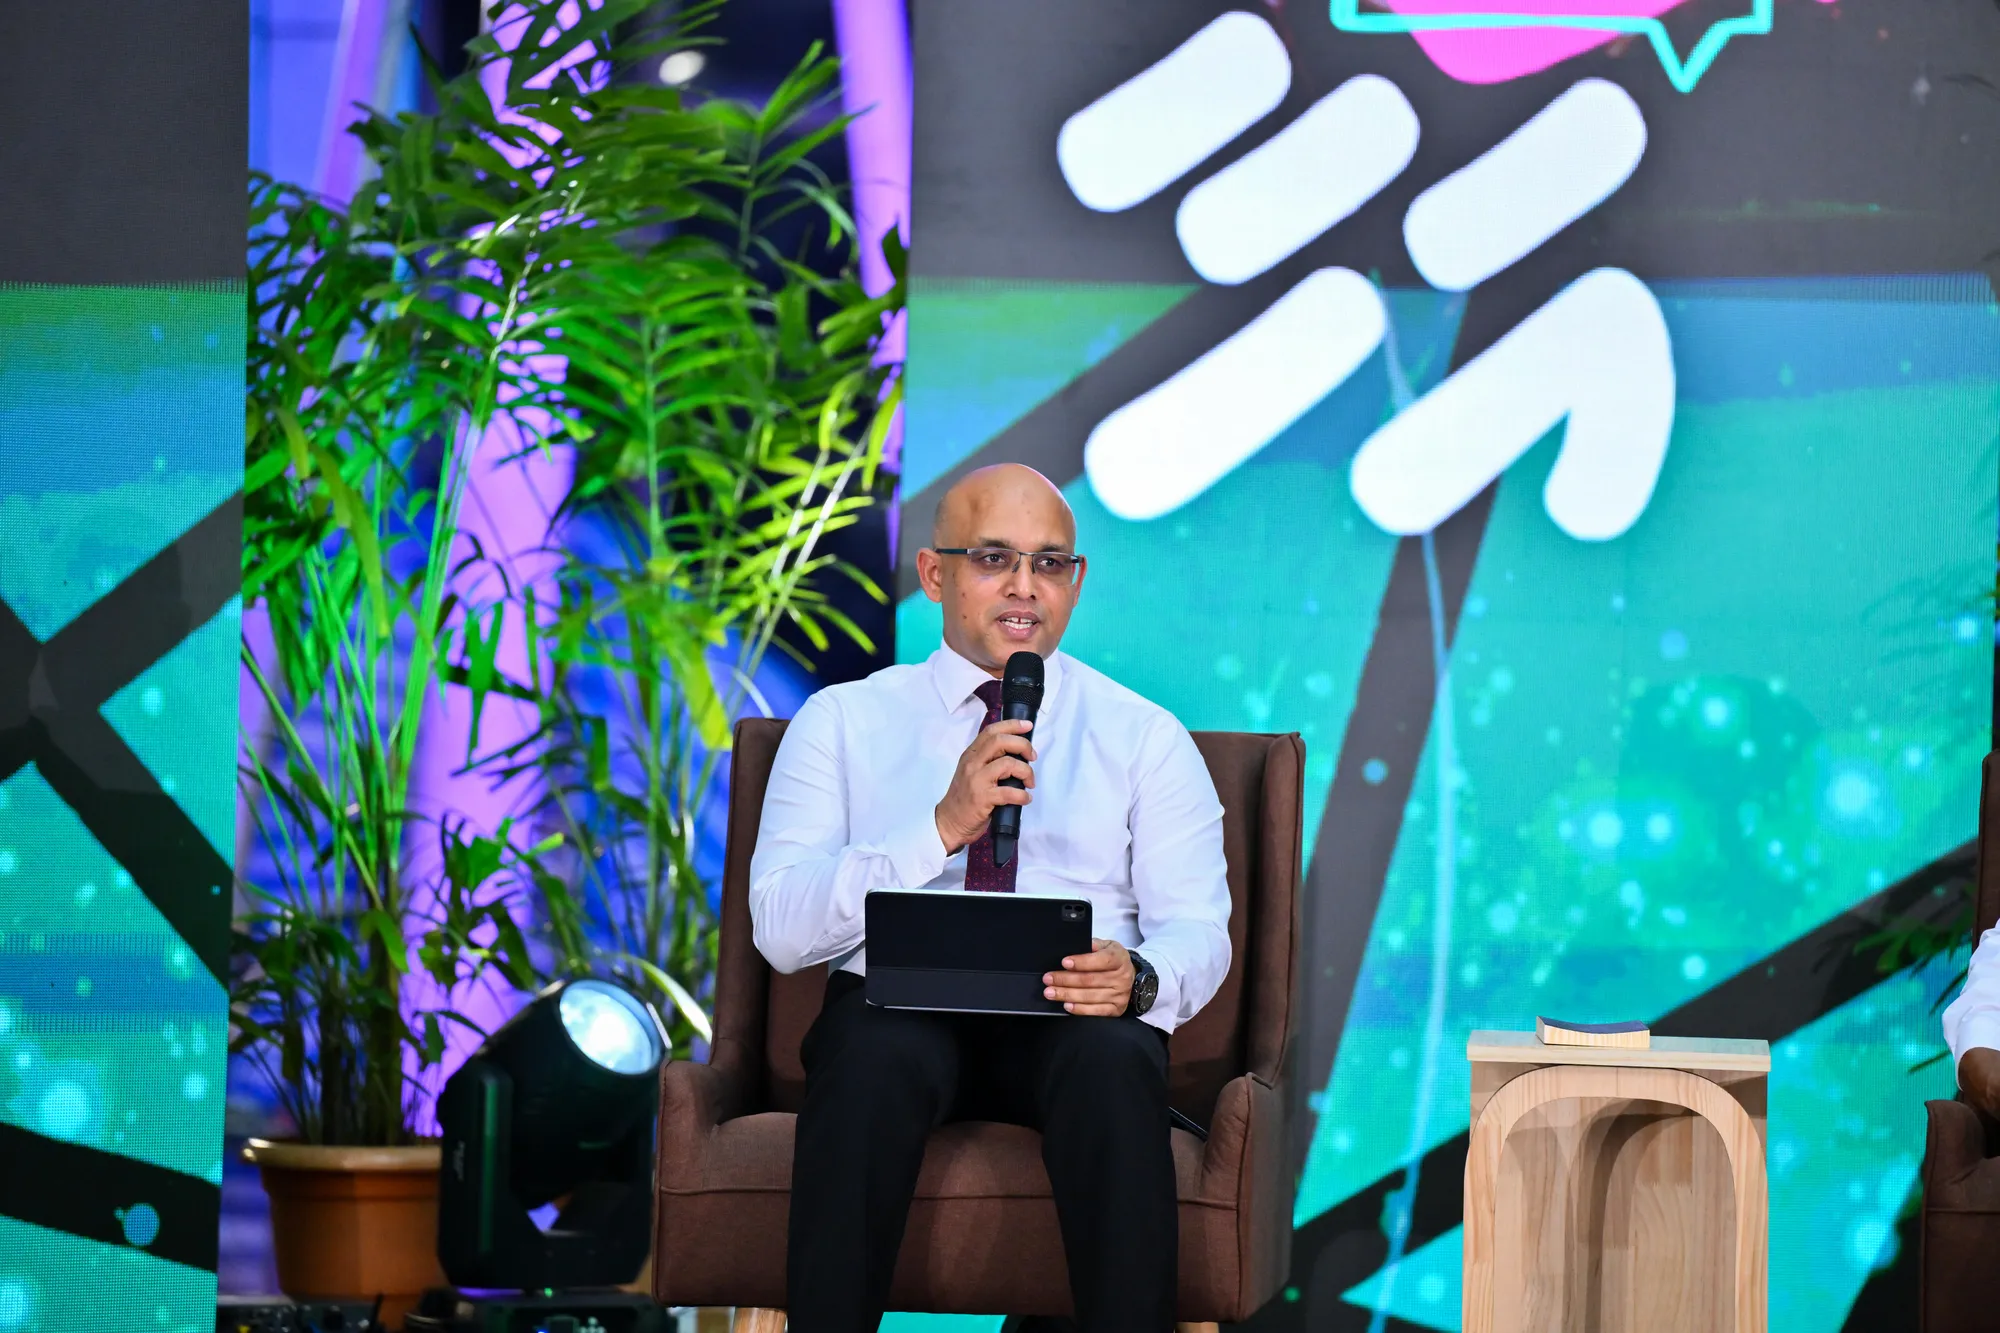
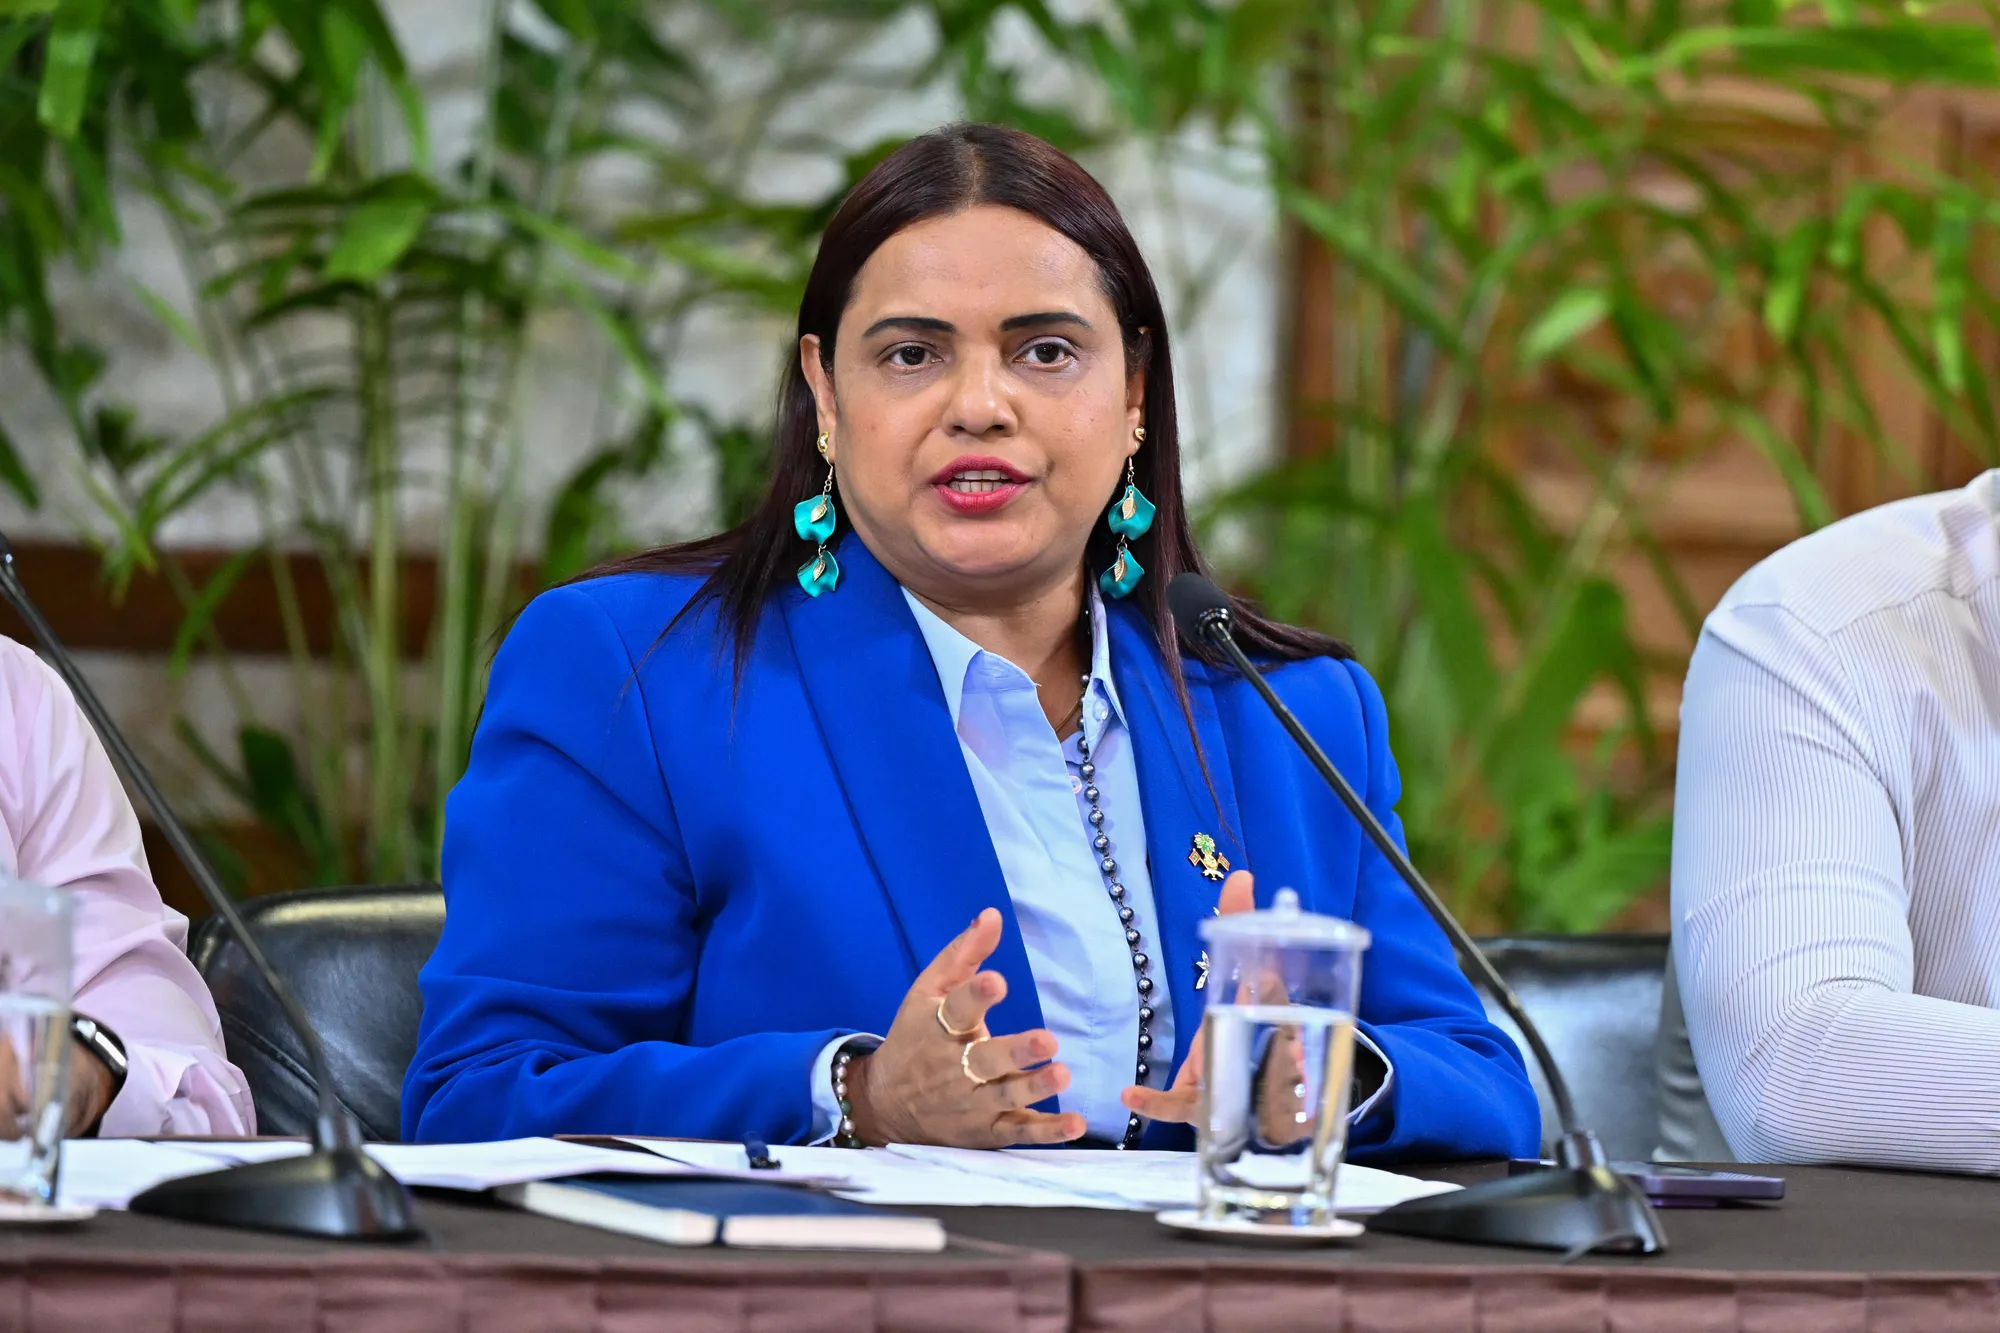
Minister of Finance Hassan Zareer has announced that the government is currently overseeing 1,273 active development projects across the archipelago.
Speaking at the ninth edition of the "Ahaa" public forum, Zareer detailed the administration's efforts to maintain infrastructure momentum while navigating significant fiscal hurdles caused by geopolitical instability in the Middle East.
Infrastructure Progress Amid Logistical Hurdles
While the government remains committed to completing all signed projects, Zareer acknowledged that harbour development—a critical component of island infrastructure—has faced setbacks. The conflict in the Middle East, which escalated in March, has severely disrupted logistics, particularly the importation of essential materials like rock boulders.
Despite these challenges, the Ministry of Finance is prioritising projects through a structured monitoring system.
"We are proceeding with projects by prioritising them in a structured manner... allocating funds based on priority and financial availability," he explained.
To date, the government has utilised MVR 4.8 billion of the MVR 8.3 billion allocated for the Public Sector Investment Program (PSIP) this year.
Fiscal Resilience and Deficit Management
The Finance Minister addressed the nation's fiscal health, expressing confidence that the state budget deficit will remain within single digits despite mounting external pressures. While the original target was 7 percent, fluctuations in global oil prices—driven by regional conflict—have pushed subsidy spending to MVR 4.3 billion, far exceeding the budgeted MVR 2.9 billion.
The total budget for the year stands at MVR 64 billion, with a deficit of MVR 8.8 billion. Although this represents an increase from last year’s MVR 6.4 billion deficit, Zareer emphasised that the administration’s proactive measures are working to stabilise the economy following the historic deficits of the COVID-19 era.
A Historic Credit Rating Upgrade
In a significant win for the administration’s fiscal reform agenda, Moody’s Investors Service recently upgraded the Maldives’ credit rating from Caa2 to Caa1, revising the outlook to "Stable." This marks the first rating upgrade for the Maldives since initial ratings were issued in 2016, ending a decade-long cycle of downgrades.
"After that consistent decline, this marks the first time we have received an upgrade," Zareer noted, adding that international financial institutions have reacted positively.
The upgrade is expected to open new avenues for financing, making it easier for the state to execute planned capital projects and restore investor confidence.
Debt Servicing and the "Light at the End of the Tunnel"
Managing national debt remains a top priority for the government. Zareer revealed that since the current administration took office, it has disbursed a staggering USD 1.42 billion toward debt servicing—a significant increase compared to the USD 400 million paid between 2013 and 2018, and USD 948 million between 2018 and 2023.
Despite the heavy burden of loan obligations, the Finance Minister offered an optimistic outlook for the future.
"Even though this has been a challenging year, we have begun to see light at the end of the tunnel," he said, adding that the milestones achieved in credit stability and debt management pave the way for "very bright days ahead" for the Maldivian economy.
Leave a comment
Comments
No comments yet. Be the first to comment!